Analyses & Studies • Publications
Indonesia’s new export controls regime: What mining, natural resources and oil & gas companies need to know
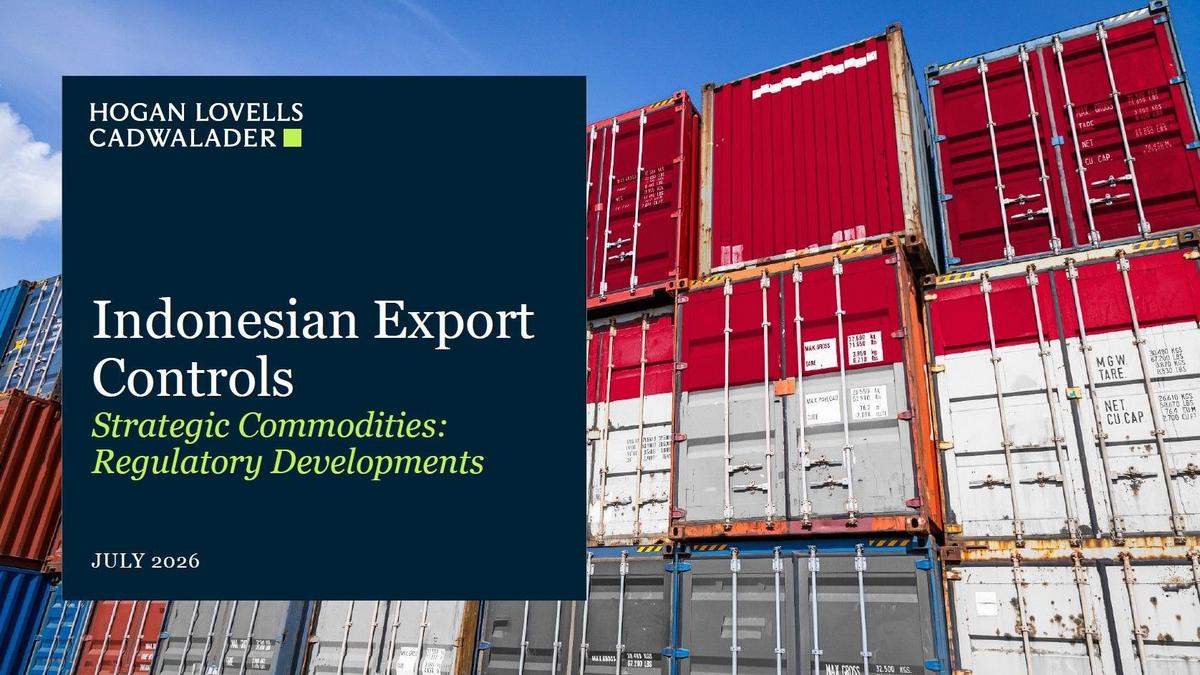
Indonesia is the world’s largest exporter of coal, palm oil, and nickel (with combined exports exceeding US$65 billion in 2025) and ranks 4th globally for liquefied natural gas. Recent plans to centralise control of the country’s strategic exports in a single state-owned entity—including setting export prices—could represent a significant intervention in global commodity markets by an important resource-producing nation and disrupt existing contractual relationships. However, the final form and level of state involvement is still uncertain following concerns raised by industry participants.
In this article, we summarise key elements of the proposed export controls (still developing in parallel with industry consultation) and discuss the practical implications for foreign companies investing in Indonesia’s mining, resources, and energy sectors, as well as companies exporting commodities from Indonesia, setting out recommended actions for companies exposed to commodity supply chains.
Background
On 20 May 2026 during an address to Parliament, President Prabowo Subianto unveiled a sweeping new framework to centralise the export of strategic commodities through a state-owned enterprise, implemented by Government Regulation No. 24 of 2026 on the Governance of Exports of Strategic Natural Resource Commodities (“GR 24/2026”).1 With the stated aim of capturing billions in lost revenue—estimated to be as much as US$908 billion between 1991 and 2024—due to under-invoicing, transfer pricing, and diversion of export proceeds as well as strengthening state oversight of strategic sectors and stabilising the Indonesia Rupiah, the framework brings coal, palm oil, and ferroalloys exports under the control of a single state-owned enterprise, PT Danantara Sumberdaya Indonesia (“DSI”), a subsidiary of the nation’s sovereign wealth fund.
The announcement of the new regulatory framework caused immediate impacts on local Indonesian markets, including a ~3% drop in the Jakarta Composite Index (JCI). Industry groups also expressed concern over future market disruption from a centralised export regime being implemented through a newly-established state-owned entity.
While GR 24/2026 remains in effect, the plan is being scaled back significantly following a meeting between DSI and major industry associations on 11 June 2026. Minutes of that meeting which included representatives from Asosiasi Pengusaha Indonesia (APINDO), the Indonesian Mining Association (IMA), Indonesian Coal Mining Association (ICMA, known locally as APBI2), Forum Industri Nikel Indonesia (FINI), and the Indonesian Palm Oil Association (IPOA, known locally as GAPKI3) were released to media.
According to reports, the new plan deviates from GR 24/2026, with DSI acting as a “facilitator” that monitors prices and supervises transactions without directly taking over existing contracts or trading relationships.4 As industry consultations continue, DSI’s eventual role has not yet been finalised and will be evaluated regularly to assess the need for future adjustments. Nevertheless, the policy change could still reshape how Indonesia’s strategic commodities reach international markets.
The new commodities export framework — How it works
DSI’s involvement as a state-owned entity in the export of strategic commodities is grounded in Indonesia’s constitutional mandate that its natural resources are controlled by the State for the greatest benefit of the people. It represents the latest evolution in a long-standing policy of using export restrictions to capture greater domestic value—a trajectory that began with the 2009 Mining Law, which established mandatory local processing of mineral ore before export. Since then, further regulations have banned the export of additional products—most recently, introducing a ban on iron ore and concentrates, including titanium slag in March 2025.5
The new framework is being rolled out in phases, but the ultimate structure and scope of DSI’s mandate will continue to develop following industry consultations:
- Phase 1 (June-December 2026): Coal, palm oil, and ferroalloy producers submit export documentation to DSI during this transitional period. While business continues as usual between exporters and foreign buyers, all export activities must now be reported to DSI.
- Phase 2 (From January 2027): Following the transitional period, DSI’s priority will be to serve as an intermediary by facilitating and overseeing exports, monitoring prices and supervising how buyers and sellers establish prices, intervening where contracts appear “abnormal” or “unreasonable”.
According to initial reports, DSI is building a digital platform to analyse transaction data on exports of strategic commodities, enabling under-invoicing to be identified on a data-driven basis. It plans to develop a pricing assessment methodology based on international principles and industry-standard price indices, taking into account product quality, commodity specifications, logistics costs, contract structure, and other commercial factors.
GR 24/2026 also introduced a broader governance framework addressing verification and traceability requirements; regulation of transportation and export insurance; and other control mechanisms that would be integrated into existing national systems such as the Customs Excise Information System and Automation (CEISA), the Indonesian licensing and permit system INATRADE, and Indonesia National Single Window (INSW) to allow for centralised data monitoring in real time. How much of this remains in the final framework is still to be seen.
It is not clear how much of GR24/2026 will remain in the final framework (as implemented) given the current efforts to scale back its original scope, but DSI’s role will be evaluated regularly to assess effectiveness and consider whether future adjustments are necessary to achieve their intended results. It remains to be seen whether the facilitator model will continue long-term or whether the Indonesian Government will eventually expand DSI’s mandate.
Commodities in scope
The initial commodities brought under DSI’s purview are coal, crude palm oil, and ferroalloys (including ferrochrome and ferronickel), each of which contribute significantly to the national export revenues, with additional commodities likely to be added at later stages. They also represent products for which Indonesia holds a strong market position. For example:
- Coal. Indonesia is the world’s largest exporter of thermal coal and accounts for more than 40% of global seaborne thermal coal trade, supplying a critical share of the coal consumed by Asian power utilities for baseload power generation.
- Nickel. Indonesia holds the world’s largest known nickel reserves and could supply as much as 70% of global nickel by the end of 2028.
- Palm Oil. Indonesia is the world’s largest producer and exporter of palm oil, supplying ~50% of global trade, making it the single most concentrated source of any major globally traded agricultural commodity and directly impacts food manufacturing, biodiesel blenders, and oleochemical producers around the world.
Initial indications are that new commodities falling under DSI’s purview may be added on a regular basis, but the Minister of Energy and Natural Resources suggested at a meeting of the Indonesian Petroleum Association in May that the upstream oil and gas sectors will not be impacted. Whether that exclusion will remain in the future is an open question.
Impact on foreign companies
Given the importance of Indonesia as a resource producer, foreign companies need to monitor developments over the next several months to understand how their businesses will be impacted as the new framework is finalised.
Despite the steps being taken to scale back the new export framework following consultation with industry groups, the plan still represents a significant structural change and raises concerns for foreign companies—whether actively investing in Indonesia’s resource sectors, exposed as exporters of affected commodities, or considering market entry.
- Review of existing contracts. DSI’s mandate is to monitor export prices and intervene where contracts are found “abnormal” and “unreasonable” though the ultimate criteria for this assessment is unknown. Even without taking over existing contracts as originally planned, this intervention creates a risk that existing pricing mechanisms will be scrutinized and renegotiated.
- Trade finance and structured finance risks. With many long-term contracts relying on offtake contracts to secure financing, the potential intervention of a state-owned entity on key terms like pricing could affect the practical operation of financing arrangements and place parties at odds with financiers.
- Regulatory uncertainty. Though industry consultations continue GR 24/2026 still provides that from 1 January 2027, commodity exports can only be carried out by the state entity—language difficult to reconcile with the scaled-back role of DSI. Given this uncertainty, companies should monitor developments and potential divergence between DSI’s stated approach and formal legal requirements as well as the practical implementation.
- Supply continuity risks. The scaled-back approach has eased immediate concerns about trade disruptions and industry concerns over buyers switching to alternative suppliers. Nevertheless, given DSI’s governance structure is still being developed and its ultimate mandate may evolve, this leaves open the possibility of supply disruptions.
- Broader regulatory and investment climate. With the JCI’s ~30% fall year-to-date, the Indonesian Rupiah hitting record lows above IDR 17,700 per US$, Bank Indonesia raising benchmark interest rates by almost 100 basis points to 5.75%, ratings agencies (e.g., Moody’s and Fitch) issuing ratings outlook downgrades, and MSCI threatening to downgrade Indonesia to frontier market status, the uncertainty around implementation of GR 24/2026 as well as the possibility of further regulation and government intervention may continue to unsettle the sector with further resource nationalism.
- Potential regulatory enquiries. A number of companies operating in the palm oil sector in Indonesia have already received summons’ from Indonesian regulators, looking into issues such as price manipulation and unlawful collusion. These type of enquiries have increased in the last 18 months, with the Indonesian government closely scrutinising pricing in key sectors for the country.
- International trade considerations. Companies should assess whether the new framework gives rise to claims under bilateral investment treaties (“BITs”), free trade agreements (“FTAs”) such as the February 2026 US-Indonesia Free Trade Agreement, or WTO commitments. In recent years, Indonesia has taken steps to terminate a number of its BITs. However, whether the terms of operative and applicable BITs and FTAs (e.g., most favoured nation and fair and equitable treatment clauses) can be reconciled with the new framework should be analysed closely.
Recommended actions
Companies exposed to Indonesian commodity supply chains should consider the following:
- Review existing long-term supply, offtake, and procurement agreements to understand how DSI’s oversight role may affect contractual arrangements—including force majeure, change of law, and price provisions.
- Monitor the transition period and watch for any divergence between DSI’s stated facilitator approach and formal implementing regulations, including withdrawing and replacing (or amending) GR 24/2026.
- Evaluate potential for price intervention and whether contractual protections (price adjustment, benchmarking, and dispute resolution provisions) are adequate.
- Assess whether the price assessment methodology ultimately implemented reflects international principles or violates price clauses in existing contracts.
- Consider supply chain diversification strategies to mitigate concentration risk.
- Assess rights under operative and applicable bilateral investment treaties or international trade obligations.
- Be aware of potential conflicts of law with other jurisdictions’ trade and investment restrictions, such as the United States and China.
- Review available protections for continued fluctuation in critical sectors like mining and oil and gas as resource nationalism and domestic resource prioritisation are pursued.
- Monitor for additional commodities being brought under the framework in subsequent notifications.
Authored by Rob Palmer, Christopher Bloch, Ben Kostrzewa, and Teguh Darmawan.
References
- Channel News Asia, Prabowo's export control move could boost Indonesia's revenues, but experts worry about stronger state hand, 22 May 2026 (available at www.channelnewsasia.com/asia/indonesia-prabowo-subianto-economy-revenue-6135986); Jakarta Globe, What We Know So Far About Danantara Sumberdaya, Indonesia's New Export Entity, 20 May 2026 (available at jakartaglobe.id/business/what-we-know-so-far-about-danantara-sumberdaya-indonesias-new-export-entity).
- Asosiasi Pertambangan Batubara Indonesia
- Gabungan Pengusaha Kelapa Sawit Indonesia.
- Straits Times, Indonesia to scale back commodity export centralisation, tighten monitoring: Sources, 11 June 2026 (available at www.straitstimes.com/asia/se-asia/indonesia-to-scale-back-commodity-export-centralisation-tighten-monitoring-sources); Reuters, Danantara Indonesia unit will not take over contracts in new export plan, meeting minutes show, 12 June 2026 (available at www.msn.com/en-us/money/news/danantara-indonesia-unit-will-not-take-over-contracts-in-new-export-plan-meeting-minutes-show/ar-AA25sMge.
- Regulation No. 9 of 2025 concerning the Third Amendment to Ministry of Trade Regulation No. 23 of 2023 on Export Policy and Regulation, dated March 6, 2025; Ministry of Finance Decree No. 6/KM.4/2025.
Source: Hogan Lovells Cadwalader